Picture a heating and cooling company heading into its busy season. The owner's best Meta ad has been running for months: a photo of a new system going in, a line about same-week installs, a button to book a free estimate. A new furnace costs a family several thousand dollars, so the owner does the obvious thing and adds one line to the ad: "0% financing for 60 months."
One of two things happens next. Meta rejects the ad, and the owner spends an afternoon trying to work out what was wrong with a photo of a furnace. Or Meta approves it, the ad runs, and the owner reasonably assumes the line was fine.
Neither outcome tells the owner what actually changed. Once that ad offers financing, Meta no longer treats it as an ad for a furnace. It treats it as an ad for a financial product, and since January 21, 2025, Meta has required every advertiser who is in the United States or targets people there to file those ads under a special ad category. That category comes with its own rules about who you can reach, and they are stricter than most owners expect. This article covers what puts an ad in the category, what you lose when it does, and how to keep offering payment plans without giving up the targeting your other ads depend on.
Meta Counts "Pay Over Time With Klarna" as a Financial Services Ad
The category is called Financial products and services. It replaced Meta's older Credit category in October 2024 and became mandatory for US campaigns on January 21, 2025. Meta's help page puts the consequence plainly: "Ads may be rejected if an appropriate category is not chosen."
Most owners assume the category is for banks, lenders and insurance agents. Meta's own list says otherwise. It covers ads that "promote or directly link to a financial product or service offer, including credit," and the examples include:
- Long-term financing
- Loans of every kind, including personal and business loans
- Consumer payment services
- "0% APR installment payments, including buy now, pay later (BNPL) and in-house installment payments"
Read the last one twice. A furniture store's "pay over time with Klarna," a med spa's monthly treatment plan, a dentist's in-house payment plan for implants and a roofer's "no interest for 18 months" all sit inside Meta's own definition. One of the two sample ads Meta shows on that help page is a service company's offer, not a bank's. Meta is not hiding the ball. It is assuming advertisers will read the page.
Two details on the list catch people out.
The link counts, not just the words. The scope covers ads that "directly link" to a financial offer. An ad that never mentions financing but sends people to your financing application page is still an ad for a financial offer.
Meta also names what is outside it. Gift cards, store rewards, financial products sold only to other businesses, and tax and accounting services. A loyalty punch card does not put you in the category. A payment plan does.
Meta Approving Your Ad Doesn't Mean It's Compliant
The obvious objection is that plenty of businesses run financing lines without the category and nothing happens. That is true, and it is exactly the trap.
Here is what it looked like in an account we manage, an online furniture store. Earlier this month, two new retargeting ads went live in the same campaign with the same closing line: "Pay over time with Klarna." The campaign had no special ad category set. Meta rejected one of the two in review. The other was approved and started delivering. Both were replaced within a day by versions without the line.
We cannot tell you for certain that the Klarna line caused the rejection. Meta's system recorded that the ad was rejected but not why. What the episode does show is the part that matters to you: the same sentence, in the same campaign, got two different answers from the same review system. An approval is one review on one day. It is not a ruling that your ad follows the policy.
That matters because rejections are not free. Meta tracks them at the account level, and repeated policy problems are one of the ways a small business ends up with a restricted ad account, which is a much bigger problem than one blocked ad. We walked through how that ladder works in Meta Rejected Your Ad. That Is Not the Emergency. Losing the Account Is. A financing line that slips through review in one ad and gets caught in the next is the kind of repeat problem you do not want on your record.
The Financial Category Costs You ZIP Codes, Not Just Age Boxes
So what do you actually give up? Meta's help page lists it: age, gender, ZIP code, audience exclusions, lookalike audiences, saved audiences and some interests are "limited or unavailable." Age is fixed at 18 to 65+. All genders are included and you cannot change that. Some interests and behaviors disappear, and you cannot exclude any of them. Lookalikes are gone, and any saved audience you load gets rewritten to fit the rules.
That list sounds brutal. For most small businesses, most of it costs less than it looks, for a reason we covered in You Think You Narrowed Your Audience. Meta Calls It a Suggestion. In a normal campaign, age, gender and interests are suggestions by default. Meta shows your ad outside them whenever it predicts that will work better. If you have been running broad targeting and letting the ad do the work, losing those boxes takes away settings Meta was already treating as optional.
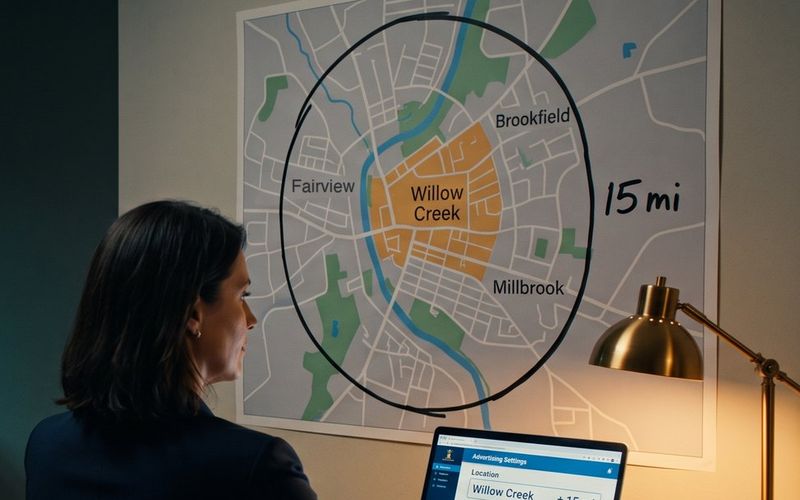
Location is different. Location is a hard limit in a normal campaign, and it is where the category takes the most from a local business. Under the category, Meta's page says you can target by country, state, region or city, "but not by ZIP code or postal code. You also can't exclude locations." And any city, address or pin you pick is widened to a 15-mile radius in the United States. Meta's own example: target Seattle and you also reach everyone within 15 miles of Seattle's city center.
Think about who that hurts. A remodeling company that serves eight affluent ZIP codes on one side of a metro, and deliberately skips the rest, loses both halves of that plan: it cannot pick the eight and it cannot exclude the others. A pool builder that only works within 20 minutes of its yard gets a 15-mile circle centered on whatever city it names, which may sit nowhere near the yard. Meta already leaks some ads outside the area you pick, which we covered in Meta Checked a Box for You. It Sends Your Ad Out of Town. The category takes away the tools you would use to tighten it.
Now compare an online store that ships to every state. It never targeted by ZIP, and broad targeting already did most of its work. For that business the category costs very little, and the honest advice is simply to turn it on for any ad that mentions Klarna, Affirm or Afterpay.
Financing Belongs in Its Own Campaign, Away From Your ZIP Code Targeting
If you are a local business that depends on precise geography, there is a cleaner answer than either hiding the financing line or putting your whole account under the category. Split the job in two.
The main campaign stays clean. No financing language in any ad in it, and no ad that links directly to your financing application. This campaign keeps your ZIP codes, your exclusions and everything else, and it does the heavy lifting of finding new customers. Your landing page can still mention that financing is available. Meta's wording targets ads that promote or directly link to a financial offer, and a service page that lists financing among a dozen other things is not that. That is our reading of the policy, not a sentence Meta has written, so do not test it by making the financing offer the headline of the page your main ads point to.
The financing campaign is declared, smaller and aimed late. Turn on the Financial products and services category at the campaign level, accept city-level targeting, and write ads where the payment plan is the point. These ads earn their keep with people who already know roughly what the job costs and are stuck on the number. Meta still lets you build custom audiences in these campaigns, so if your site traffic is large enough, people who visited your pricing or service pages are a natural fit. What you cannot do there is build a lookalike or carve audiences by age.
The split also tells you something useful. If the financing campaign brings in booked jobs at a reasonable cost, financing is doing real work for your business. If it barely moves, you have learned that price was never the objection, and you can stop paying for the line.
"0% for 60 Months" Brings Federal Disclosure Rules With It
Meta's policy on financial ads has one more line that most owners skip: advertisers "are required to comply with disclosure requirements set by law." For consumer financing in the United States, that law is the federal Truth in Lending rules, known as Regulation Z, and they apply to the words in your ad, not just to the loan paperwork.
The rule that catches most small businesses works on what the regulation calls triggering terms. If your ad states any of these:
- the number of payments or the repayment period ("60 months," "36 easy payments")
- the amount of any payment ("$99 a month")
- the amount or percentage of a down payment ("only $500 down")
- the amount of any finance charge
then the same ad must also state the down payment (if one is required), the full terms of repayment and the annual percentage rate, written as "APR." Vaguer phrases such as "monthly payment terms arranged" do not trigger it. "0% for 60 months" does, because "60 months" is a repayment period.
"No interest" offers on store credit cards have their own rule. If the interest is deferred, meaning it gets charged back to the purchase date when the balance is not paid off in time, the ad must say "if paid in full" along with the deadline, right next to the claim, and state that interest will be charged from the purchase date if the balance is not paid in full. That is why the compliant version reads "No interest if paid in full within 12 months" instead of "12 months no interest."
You do not have to write this from scratch. Most businesses that offer financing do it through a lender, and those lenders usually supply ad copy and disclosures they have already approved. Use theirs, word for word, and keep the full terms one tap away. This is general guidance, not legal advice, and a business running a large financing program should have its ads reviewed by someone who does this for a living.
When Financing Doesn't Belong in the Ad at All
Not every business that offers payment plans should advertise them. Financing earns a place in the ad when the price is the main reason people say no and the purchase is big enough that a monthly number changes the decision. A new roof, a furnace, a set of implants, a pool table, a sofa. For a $250 drain cleaning, or a service people buy on urgency rather than price, a financing line adds a category and a disclosure burden for very little gain.
There is also a quieter cost. Every phrase in an ad competes for the few seconds people give it. If your customers' real hesitation is trust or timing, a payment plan in the headline answers a question nobody was asking. Look at what your lost estimates actually say before you assume the number is the problem.
If you keep financing out of the ads, keep it in the sales process. Put it on the estimate, have whoever answers the phone mention it, and keep a clear page about it on your site. The customers who need it will find it at the point where it matters, which is when they are looking at a real price.
One Financing Line in a Video Caption Puts the Whole Ad in Meta's Special Ad Category
- Search your live ads for payment words. Financing, months, APR, monthly, Klarna, Affirm, Afterpay, payment plan, "no interest." Check primary text, headlines, descriptions, images and video captions.
- Check where each ad links. Any ad that sends people straight to a financing application counts, even with no financing words in it.
- Decide per business, not per ad. If you sell online and do not depend on ZIP targeting, turn the Financial products and services category on for any campaign that mentions financing. If you depend on precise local targeting, split financing into its own campaign.
- Rewrite every financing line to match the disclosure rules, using your lender's approved wording where you have it.
- Keep financing on your estimates and your site even where you take it out of the ads.
- Judge the financing campaign on booked jobs, not leads, and keep it only if it earns its place.
If your business sells homes, loans or leases rather than furnaces, the same mechanism runs under a different category, which we covered in Meta Treats Every Real Estate Ad as a Housing Ad. That Takes Away Most of Your Targeting. And if you would rather have someone sort your campaigns into the right categories and keep your targeting where it counts, that is everyday work for our Facebook and Instagram ads team. Either way, read Meta's list once. It is shorter than one rejected ad.